How to Pay for IOP in Los Angeles [Updated 2026]

You can pay for an Intensive Outpatient Program (IOP) in Los Angeles with health insurance, the program’s self-pay rate, pre-tax HSA or FSA money, or a payment plan or medical financing. Some programs also charge less if your income is low.
Without insurance, a standard 8–12 week IOP typically costs $6,000 to $21,000 in total. With an in-network plan, most people pay $0 to $3,000 a month out of pocket. Here’s how IOP pricing works.
Which IOP Payment Option Fits Your Situation?
Which option to start with depends mostly on your insurance. Most people end up combining two or three, usually insurance first, then HSA money or a payment plan for the part insurance doesn’t pay. Find the row that matches you below.
| Your situation | Start with | Also consider |
|---|---|---|
| You have insurance, and the program is in-network | Your insurance | HSA or FSA money for your share |
| You have insurance, and the program is out of network | A single case agreement | The self-pay rate, if it costs less, or a superbill |
| Leaving PHP or a hospital stay | Get IOP approved before you leave | HSA or FSA money for your share |
| No insurance | The self-pay rate, with a written estimate | A payment plan, or signing up for Covered California |
| High-deductible plan | HSA money toward your deductible | A payment plan for the rest |
| Tight budget | Sliding-scale fees or scholarships | Low-cost community clinics |
| Insurance stops paying partway through | An appeal | Paying the self-pay rate while you wait |
Did you know most health insurance plans cover mental health treatment? Check your coverage online now.
How Do You Use Health Insurance to Pay for IOP?
If you have health insurance, through your job or a plan you bought yourself, start there. A California law called SB 855 requires most plans sold in the state to cover IOP when it’s medically necessary, which means your symptoms call for this level of care. Plans that a large employer pays for out of its own money (“self-funded” plans) follow federal law instead, so SB 855 doesn’t apply to them. The benefits check below tells you what your plan covers either way. More on California’s mental health parity law.
How Do You Find Out What Your Insurance Covers for IOP?
Ask the program for a benefits check. Their admissions team takes your insurance card information, calls your insurance company, and tells you whether the program is in your network and about how much you’ll pay. Most programs do this for free. You can also call the mental health or behavioral health number on the back of your insurance card yourself. Either way, ask:
- Is the program in my plan’s network?
- How much is my deductible, and how much of it have I met this year?
- Do I pay a copay or coinsurance for IOP?
- Does IOP need prior authorization, and how many days will you approve to start?
- What’s my out-of-pocket maximum?
- Do I have out-of-network benefits?
If you’re in the Los Angeles area, we’d be happy to run a benefits check for you. Request a free benefits check or call 888-449-0852.
What’s the Difference Between In-Network and Out-of-Network IOP?
An in-network IOP has a contract with your insurance company that sets its price, so you only pay your normal share, like a copay. In-network care generally results in lower out-of-pocket costs than out-of-network care.
An out-of-network IOP has no contract with your insurance company. Your plan may cover a smaller portion of the cost, require a separate out-of-network deductible, or provide no out-of-network benefits at all. The program can also bill you for whatever your insurance doesn’t pay.
Most programs send the bill to your insurance company for you, even when they’re out of network. But if you pay an out-of-network program yourself, your insurance company never gets a bill, so ask the program for a superbill. It’s a detailed receipt that lists your diagnosis and the services you received, in the codes insurance companies use. Send it to your insurance company, and if your plan has out-of-network benefits, it may pay you back for part of what you spent. Not every program provides superbills, so ask before you pay.
Can Insurance Cover an Out-of-Network IOP?
Sometimes. You can ask your insurance company to pay for an out-of-network IOP as if it were in-network, just for your treatment. This is called a single case agreement. Insurers usually agree only when no in-network program can meet your needs, for example:
- No in-network program within a reasonable drive
- A therapist who speaks your language or shares your culture, like a Mandarin-speaking therapist
- A specialty the in-network programs don’t offer
Ask the program’s admissions team to request one. They’ll ask you why this program is the better fit for you, then put the request together and send it to your insurer. It isn’t always approved, but it’s worth asking before you rule out a program you like.
What Will You Pay Out of Pocket at an In-Network IOP?
At an in-network IOP, your costs usually come from three parts of your plan:
- Your deductible. This is the amount you pay yourself each year before your insurance starts paying.
- Your copay or coinsurance. Once you’ve met your deductible, you pay either a set amount for each program day (a copay) or a percentage of each day’s cost (coinsurance). Insurance pays the rest.
- Your out-of-pocket maximum. This is the most you’ll pay in a year. Once you reach it, your insurance pays for all covered care for the rest of that year.
Because IOP runs several days a week for a couple of months, you may meet your whole deductible during the program. Our guide to how much IOP costs with insurance walks through the math.
After you start, your insurance company may mail you an Explanation of Benefits (EOB). It looks like a bill, but it only lists what the program charged and what your plan paid, and many say “this is not a bill” at the top. If you’re not sure whether you owe anything, call the program’s admissions team before you pay.
Contact us today to schedule an initial assessment or to learn more about our services. Whether you are seeking intensive outpatient care or simply need guidance on your mental health journey, we are here to help.
Does Your Insurance Have to Approve IOP First?
Usually, yes. Before you start, your insurance company has to agree that you need this level of care, which is called prior authorization. The program’s team sends that request for you, so there’s no paperwork on your end.
Most insurance companies won’t approve the whole program at once. They approve a certain number of days, then check how you’re doing before approving more. That means your insurance company can stop approving days before you and your care team think you’re ready to finish. More on how insurance approves and covers IOP.
If you’re stepping down from PHP or a hospital stay, ask your current care team to contact the IOP’s admissions team a few days before you leave. That way your first IOP days are approved before your last day, and you don’t go without care in between.
What Can You Do If Insurance Denies IOP or Cuts It Short?
You can appeal, whether your insurance company denies IOP before you start or stops approving days partway through. In California, it usually goes in three steps:
- Peer review. Your clinician gets on a phone call with a doctor who works for your insurance company and explains why you need IOP.
- An appeal to your plan. If the answer is still no, file a formal appeal (also called a grievance) with your insurance company. Ask the program to help you with it. Your plan generally has 30 days to decide, and urgent cases are decided faster.
- Independent Medical Review. If your plan still says no, or 30 days go by without a decision, ask for an Independent Medical Review. Doctors who don’t work for your insurance company review your case. It’s free, and if they decide you need the care, your plan has to cover it. Your plan’s denial letter tells you where to ask for the review, usually the Department of Managed Health Care (DMHC). If waiting would seriously put your health at risk, you can go to the DMHC right away.
While you wait, many programs let you keep coming and pay the self-pay rate for those days, or put them on a payment plan. Some insurance companies pay for those days later if you win the appeal, but only count on that if you have it in writing.
How Do You Pay for IOP Without Insurance?
If you don’t have insurance or choose not to use your insurance benefits, you may be able to pay for IOP directly through a self-pay rate. Costs vary by program, so it’s important to ask what the rate includes and whether payment plans or other financial options are available.
Find Out What the Self-Pay Rate Covers
Ask the program’s admissions team for its self-pay rate. Find out what it includes, like group therapy, individual therapy, psychiatry, and evaluations, and whether paying upfront lowers it.
Get a Written Cost Estimate
Under the federal No Surprises Act, if you’re uninsured or not using insurance, the program has to give you a written cost estimate, called a Good Faith Estimate, before you start. Ask for it when you schedule your first day. If your final bill is $400 or more above the estimate, you have 120 days to dispute it.
Are you covered for treatment?
LAOP is an approved provider for Blue Shield of California and Magellan, while also accepting many other major insurance carriers.
Check Coverage Now!Get Insurance Through Covered California
You may be able to get a plan through Covered California, the state’s health insurance marketplace. Every plan covers mental health care. If you recently lost insurance through your job, or moved, you have 60 days to sign up. Otherwise, open enrollment for 2027 runs November 1, 2026, to January 31, 2027. Coverage starts weeks after you sign up, so it probably won’t pay for your first weeks of IOP, but it can cover the rest of the program and the therapy after it.
Can You Use an HSA or FSA to Pay for IOP?
Yes. Money in a health savings account (HSA) or flexible spending account (FSA) comes out of your paycheck before taxes, so you save what you’d otherwise pay in income tax on it. The IRS counts psychiatric care as a medical expense (Publication 502), so either account can pay your deductible, copays, coinsurance, or the full self-pay rate. It can also cover prescriptions and the cost of getting to and from the program.
The main difference is when you can use the money:
- FSA. You get an FSA through your employer. You can spend your whole year’s amount (up to $3,400 in 2026) starting on the first day of your plan year, even before it’s come out of your paychecks. Money you don’t use by the end of the year is usually lost, though some plans let you carry over up to $680.
- HSA. You need a high-deductible health plan to have one, and you can only spend what’s already in the account. If you haven’t put in this year’s maximum ($4,400 for yourself or $8,750 for a family in 2026), you can add more now and use it for IOP right away. Money you don’t use rolls over every year and stays yours if you change jobs.
Pay the program with your HSA or FSA card, or pay another way and pay yourself back from the account later. Either way, keep the program’s itemized statements in case your HSA or FSA asks you to show what the money paid for.
Are There Payment Plans or Financing for IOP?
Often, yes. Ask the program about a payment plan first, and use medical credit cards or loans only for what’s left, since they usually charge interest and a payment plan often doesn’t.
How Do IOP Payment Plans Work?
With a payment plan, you usually pay part of your bill upfront and the rest in monthly payments. It can cover the self-pay rate or whatever you owe after insurance. Terms vary a lot, so ask:
- Is there interest or a fee?
- How much is due upfront?
- Can the payments stretch over the whole program, or continue after I finish?
- What happens to the plan if insurance stops paying partway through?
Get the plan in writing before your first day.
How Do Medical Credit Cards and Personal Loans Work for IOP?
For whatever a payment plan doesn’t cover, there are two common options:
- Medical credit cards, such as CareCredit. Many offer a no-interest period, often 6 to 24 months. Many also use deferred interest, which means that if any balance is left when the no-interest period ends, you’re charged interest all the way back to the day you made the purchase. Check that the program accepts the card before you apply.
- Personal loans. You get a fixed interest rate and the same payment every month, which is easier to plan around. Compare rates from a few lenders, and check for origination fees (a one-time fee some lenders charge to start the loan).
Rediscover Life at Los Angeles Outpatient Center
Get the compassionate mental health support you deserve. We're here to help you reclaim joy, wellness, and a brighter future.
Our Facility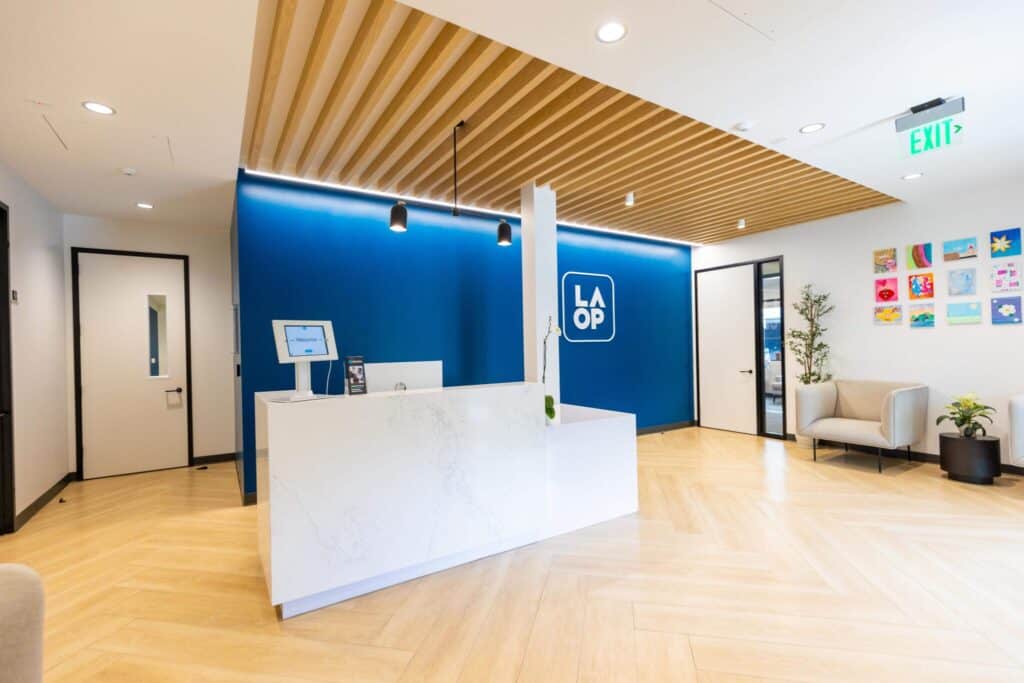
Can You Pay Less for IOP If Your Income Is Low?
Yes, some programs lower the price if your income is low, but those spots are limited. This usually works one of two ways:
- Sliding-scale fees. The program sets your price based on your income and how many people are in your household.
- Scholarships. The program pays for part or all of the cost for a set number of people who can’t afford it.
Either way, you’ll usually need to show proof of income, like recent pay stubs or last year’s tax return. Ask who qualifies, how much it covers, and how to apply.
Both are more common at nonprofits and community clinics than at private programs. FindTreatment.gov, the federal government’s treatment locator, lets you search for programs that offer sliding-scale fees or free care. Our guide to mental health resources in Los Angeles lists lower-cost clinics across the county, and NAMI Greater Los Angeles County offers free help finding care.
Check Your IOP Coverage With LAOP
LAOP’s admissions team can check your coverage before you commit to anything. To get started, request a free benefits check or call 888-449-0852 any time, day or night. If you’re paying without insurance, we’ll walk through the self-pay rate and your options for spreading it out.
LAOP runs a CARF-accredited IOP in Culver City. We work with Aetna, Blue Shield of California, Cigna, TRICARE, and TriWest. If your plan isn’t on that list, we can still check it, and if we’re out of network, we can ask your insurer about a single case agreement. Our admissions team handles every billing question, so money never comes up in your therapy sessions.
If you’re in crisis or thinking about suicide, call or text 988 to reach the Suicide & Crisis Lifeline. It’s free and confidential, and someone answers any time of day or night.

Share This Post

TREATMENTS WE OFFER
Are you covered for treatment?


LAOP is an approved provider for Blue Shield of California and Magellan, while also accepting many other major insurance carriers.
Check Coverage Now!